Henderson Market Digest

Market data through September 14, 2026

View the Seven Hills Market Report

Henderson Median List Price

~$548,000

Avg Days On Market

~21 days

Call Bev (702) 857-6729

Approximate community statistics, not Bev Prock's personal sales. Source: Las Vegas REALTORS (LVR) / GLVAR, accessed September 14, 2026.

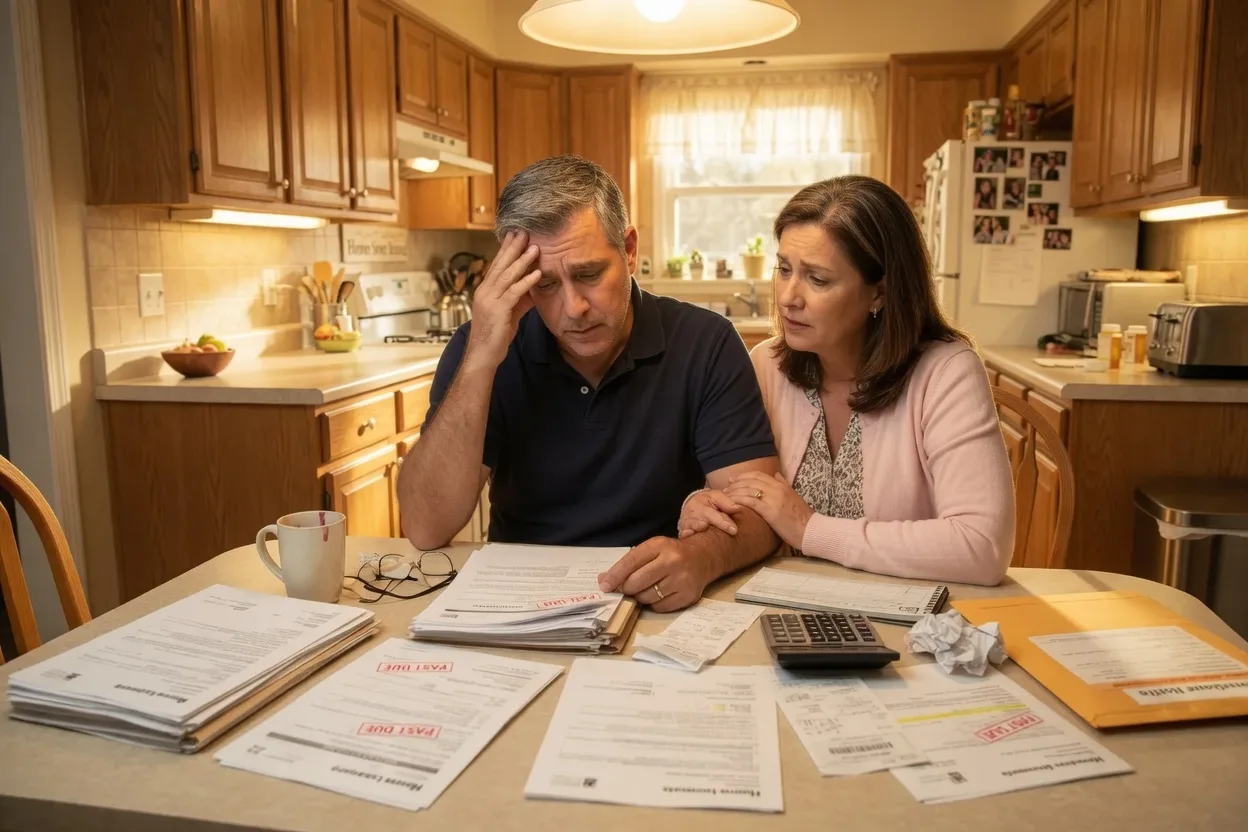
Couple reviewing financial documents with their real estate agent at a table
Distressed Properties

Expert Guidance Through Difficult Times

If you are facing foreclosure, struggling with mortgage payments, or dealing with a distressed property, Bev Prock is here to help. As a Short Sale and Foreclosure Specialist (SFR) with 18 years of experience, she can help you understand the options available and work through them with compassion and discretion. No legal, tax, or credit outcome is ever guaranteed.

Understanding Your Options

What Are Distressed Properties?

A distressed property is a home where the owner is facing financial hardship and may be unable to continue making mortgage payments. This situation can feel overwhelming, but you are not alone. There are several paths that may be available, and the most important step is reaching out for guidance early, before decisions are made under pressure.

Bev has been helping homeowners in Henderson and Las Vegas navigate these situations since 2008. Her SFR designation reflects specialized training in short sales, pre-foreclosure options, and foreclosure alternatives. She works with homeowners to understand the options available and thinks outside the box to find a workable path for each person's unique circumstances.

Short Sale and Foreclosure Specialist (SFR) certification logo

What the SFR training covers:

  • Short sale negotiation and lender approval processes
  • Lender requirements and timelines for distressed properties
  • Foreclosure alternatives including deed-in-lieu and loan modification
  • Referrals to attorneys, tax advisers, and HUD-approved housing counselors for the questions real estate agents do not answer

Before you decide, talk to the right professionals

Bev is a real estate agent, not an attorney, tax adviser, or HUD-approved housing counselor. A short sale, deed-in-lieu, or foreclosure can affect your credit, your tax situation, and any remaining loan balance, and those outcomes vary by lender and by circumstance. No particular result is promised or guaranteed.

Bev recommends that any homeowner facing financial hardship consult an attorney, a tax adviser, and/or a HUD-approved housing counselor before signing anything or making a decision. Those professionals can explain your rights and the consequences of each option. Bev is glad to coordinate with them so the real estate side of your situation stays on track.

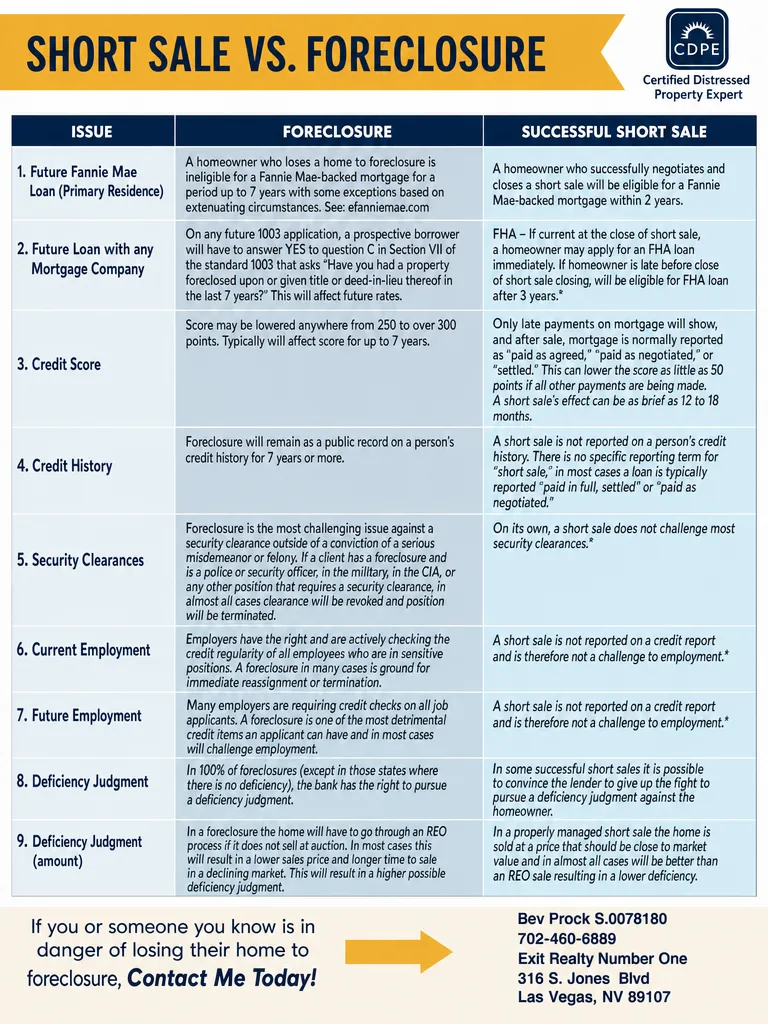
Short Sale vs. Foreclosure comparison flyer from Bev Prock

01

What Is a Short Sale?

A short sale happens when a homeowner sells the property for less than the amount still owed on the mortgage and the lender agrees to accept the sale proceeds. It is one of several alternatives to foreclosure. Lenders may or may not release the borrower from the remaining balance, and the effect on credit varies by lender and circumstance, so there is no single guaranteed outcome.

The lender must approve the short sale before the home can close. That approval process typically requires a hardship letter, financial documentation, a listing price backed by market data, and a buyer's offer. Bev's SFR training helps her assemble a complete package and work through the lender's requirements, and she will coordinate with your attorney, tax adviser, or HUD-approved housing counselor as needed.

What a short sale can involve:

  • A potential alternative to foreclosure, depending on your situation and the lender's requirements
  • Sale terms, including how any remaining balance is handled, are negotiated with the lender and confirmed in writing
  • More control over the timing and terms of the sale than a foreclosure process may allow
  • Credit, tax, and deficiency outcomes vary, so confirm the details with your own advisers before committing
02

What Is Pre-Foreclosure?

Pre-foreclosure is the period after you fall behind on your mortgage payments but before the lender has completed the foreclosure process. It is an important window, because acting early generally preserves the most options.

During pre-foreclosure, the lender may send notices of default and begin the process of setting a foreclosure date. Foreclosure is not inevitable, but every situation is different. Some homeowners resolve their situation during this window through a short sale, a loan modification, or another arrangement; results vary and none are guaranteed. The sooner you act, the more options tend to remain open to you.

Tips for making the most of pre-foreclosure:

  • Contact an experienced agent early, before the foreclosure date is set
  • Gather your financial documents, hardship letter, and mortgage statements
  • Keep lines of communication open with your lender and loss mitigation department
  • Understand the deadlines in your state so you never miss a response window
  • Do not ignore the notices, every day of delay narrows your options
03

What Are My Options When Facing Foreclosure?

Foreclosure is not necessarily your only option, but which alternatives are available depends on your lender, your loan, and your specific financial situation. Bev will review your circumstances and help you understand the options to explore. Whether any option works out is never guaranteed, and your attorney, tax adviser, or HUD-approved housing counselor can help you weigh the trade-offs.

Short Sale

Sell the home for less than is owed, with the lender's approval to accept the sale proceeds. Whether any balance remains is negotiated with the lender.

Loan Modification

Ask your lender to change the terms of the loan, such as the rate or the term, so payments can become more affordable. Approval is never guaranteed.

Deed-in-Lieu

Voluntarily transfer ownership back to the lender. The lender must agree, and the terms, including any remaining balance, should be confirmed in writing.

Forbearance Agreement

Ask the lender to pause or reduce payments temporarily, with a plan for catching up over time. Terms vary and are set by the lender.

04

How Does Bev Help With Distressed Properties?

Bev's approach is built on integrity, knowledge, commitment, and professionalism. She listens to your needs, keeps you in the loop at every step, and thinks outside the box to make your transaction successful. Here is how she walks through a distressed situation with you.

  1. 01

    Listen to your situation. Bev begins by understanding your unique circumstances, your goals, and what you are hoping to achieve.

  2. 02

    Review your options. Together you explore every available path, from a short sale to a loan modification, so you can make an informed decision.

  3. 03

    Build a clear plan. Bev creates a step-by-step plan tailored to your goals and communicates it clearly so you always know what comes next.

  4. 04

    Manage the paperwork. She handles the lender communications, documentation, and deadlines so nothing falls through the cracks.

  5. 05

    Support you through closing. Bev stays with you all the way through the final steps, keeping you in the loop and making sure the process moves forward smoothly.


"Integrity, Knowledge, Commitment and Professionalism are the core of everything I do. I will listen to your needs and want to establish our goals together. You will continually be in the loop during the entire process."
Bev Prock
Realtor, SFR, GRI

You Are Not Alone In This

If you are facing foreclosure or a distressed situation, Bev is here to help you understand your options and work through the decisions ahead. Call her anytime. There is no judgment, only help.